
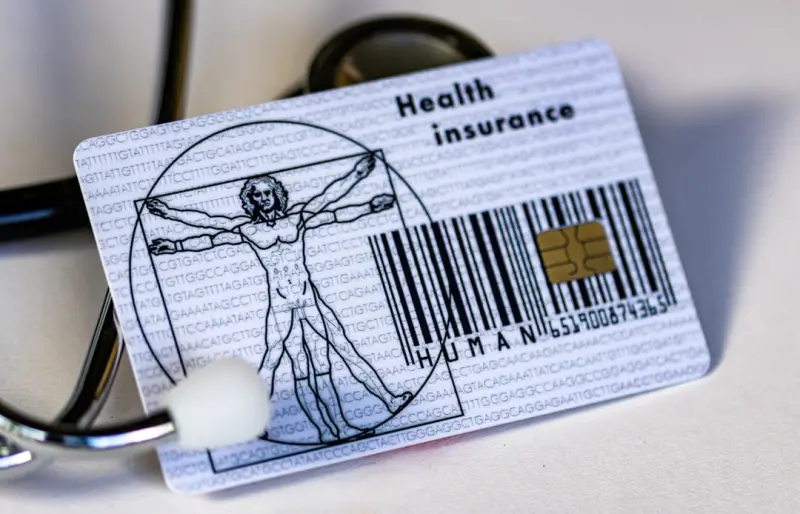
When I first landed my first health insurance plan, it felt like I’d been handed a thick, cryptic manual and told, “Good luck.” Over the years, the paperwork never truly went away; it simply morphed. Today, with telehealth, wellness apps, and data‑driven health programs, the same insurance card can be a gateway to a proactive health strategy rather than just a safety net.
Reframing Insurance as a Wellness Engine
Most of us still think of health insurance in the traditional sense: a shield against catastrophic bills. That mindset is limiting. If you treat your policy as a resource hub—one that funds preventive care, personalized coaching, and digital tools—you’ll start to see health insurance as an engine that drives continuous improvement.
Here’s how to flip the script:
- Audit your benefits quarterly. Plans evolve, and so do the services they cover. A wellness incentive that wasn’t on your radar six months ago might be a perfect fit for a new fitness goal.
- Leverage telehealth. Virtual visits are no longer a novelty; they’re a mainstream, cost‑effective way to stay on top of routine check‑ups and chronic condition management.
- Tap into employer‑sponsored wellness programs. Many companies partner with insurers to provide coaching, nutrition counseling, and mental‑health resources at little or no out‑of‑pocket cost.
The Power of Preventive Care Credits
Preventive services—annual physicals, immunizations, cancer screenings—are often covered 100 % when you stay in‑network. Yet many policyholders skip them, assuming they’ll be “covered later.” The reality is that early detection not only saves lives but also reduces future out‑of‑pocket expenses dramatically.
Make a habit of scheduling your annual physical before the end of the calendar year. Set a reminder in your calendar, treat it like a critical business meeting, and watch the ripple effect: a clean bill of health can unlock lower premiums during renewal periods, especially if your insurer offers “wellness discounts” for demonstrated preventive compliance.
Turning Data Into Action
Modern insurers collect a wealth of data—from pharmacy claims to wearable device metrics. The key is to request access to your personal health dashboard. Once you have it, you can:
- Identify medication adherence gaps and set up automatic refill alerts.
- Spot trends in blood pressure or glucose levels that may warrant a conversation with your provider.
- Use personalized health scores to negotiate better rates for supplemental benefits.
If your plan doesn’t automatically provide a dashboard, ask your HR department or the insurer’s member services team. The extra few minutes of inquiry can unlock a suite of actionable insights.
Wellness Incentives: More Than a Free Gym Membership
Many policies include “wellness incentives” that go beyond the typical gym‑membership reimbursement. These can be:
- Health‑coach stipends. Some insurers allocate a modest monthly credit for virtual coaching sessions. A 30‑minute call can help you set realistic nutrition goals or develop stress‑management techniques.
- Digital‑app reimbursements. From meditation platforms to chronic‑disease management apps, the credit can offset subscription fees that would otherwise eat into your personal budget.
- Outcome‑based rewards. Programs that track measurable health improvements—like a 5 % reduction in cholesterol—may offer cash back or premium discounts.
Don’t let these credits sit idle. Track them in a simple spreadsheet, and treat each reimbursement as a line item in your personal health investment portfolio.
Strategic Use of Health‑Savings Accounts (HSAs) and Flexible Spending Accounts (FSAs)
If your employer offers an HSA or FSA, you’re holding a tax‑advantaged pool of money that can be strategically deployed:
- Invest HSA funds in low‑cost index funds to grow your balance over time. The earnings are tax‑free when used for qualified medical expenses.
- Use FSA dollars for preventative services that are not covered 100 %—like specialized vision therapy or alternative therapies that have a physician’s prescription.
- Plan your yearly medical expenses (e.g., orthodontic work, planned surgeries) to maximize the use of these accounts before they expire.
The synergy between your insurance benefits and these accounts can create a financial cushion that turns unexpected health costs into manageable, even predictable, events.
Beyond the Basics: Integrating Mental‑Health Coverage
Mental health is no longer a fringe benefit; it’s a core component of comprehensive care. Yet many employees underutilize their mental‑health benefits because of stigma or confusion about the process. To make the most of this coverage:
- Identify the network of therapists covered under your plan. Many insurers provide an online directory with user reviews, making it easier to find a good match.
- Take advantage of “tele‑mental‑health” services. Video sessions are often covered at parity with in‑person visits, and they eliminate commuting time.
- Explore employer‑sponsored Employee Assistance Programs (EAPs). These programs typically offer a set number of free counseling sessions, plus referrals to specialists.
When mental health is actively managed, you’ll notice better focus, fewer sick days, and a measurable boost in overall productivity.
Leveraging Community Resources Through Your Insurer
Many large insurers partner with community health organizations to provide additional resources—nutrition workshops, smoking‑cessation programs, and chronic‑disease support groups. These services are often free or heavily subsidized. To tap into them:
- Visit your insurer’s member portal and look for a “community resources” section.
- Ask your primary care provider for referrals that are covered under your plan. A simple referral can unlock a series of free educational webinars.
- Participate in local health fairs that the insurer sponsors; they’re great opportunities to get free screenings and learn about new wellness tools.
Case Study: Turning an Insurance Benefit Into a Career Asset
One of my clients, a mid‑level manager at a tech firm, was frustrated by the rising cost of his family’s health care. After a deep dive into his policy, he discovered a wellness incentive that offered a $200 annual credit for enrolling in a digital weight‑management program. He combined the credit with a free virtual health coach provided by the insurer.
Within six months, he lost 12 % of his body weight, lowered his blood pressure, and qualified for a 5 % premium reduction during renewal. The savings—combined with improved energy levels—directly impacted his performance at work, leading to a promotion. This story illustrates how a proactive approach to insurance benefits can translate into tangible career growth.
Practical Checklist for Maximizing Your Health Insurance
- Read your Summary of Benefits and Coverage (SBC) cover page.
- Identify all preventive services covered at 100 %.
- Log into the member portal to locate wellness incentives, digital‑app credits, and community resources.
- Set up an HSA or FSA contribution plan aligned with your expected medical expenses.
- Schedule at least one tele‑health visit each quarter for routine check‑ins.
- Track usage of each benefit in a personal health spreadsheet.
- Revisit your plan during open enrollment; compare any new preventive or mental‑health services added.
By treating your health insurance like a dynamic toolkit rather than a static safety net, you’ll find more avenues to stay healthy, save money, and even boost professional performance.
Future‑Proofing Your Coverage
The health‑insurance landscape is evolving rapidly. Emerging trends include:
- Value‑based care contracts. Insurers are rewarding providers for outcomes rather than volume, meaning you’ll see more coordinated care plans focused on long‑term health.
- Integrated digital health ecosystems. Platforms that combine wearable data, pharmacy records, and telehealth into a single interface are becoming mainstream.
- Personalized preventive pathways. Using AI, insurers can now suggest individualized preventive actions—like a specific screening schedule based on your genetic profile.
Stay ahead by regularly checking your insurer’s news updates and by asking your HR department how new initiatives will affect your benefits. The more informed you are, the better you can position yourself to reap the next wave of health‑insurance innovations.
Conclusion: Make Your Insurance Work for You
Health insurance is no longer a passive contract; it’s an active partnership. By auditing benefits, embracing telehealth, leveraging data, and tapping into wellness incentives, you transform a monthly expense into a strategic advantage. The result? Better health outcomes, lower out‑of‑pocket costs, and a clearer path to both personal and professional goals.
Take the first step today: log into your member portal, locate one benefit you’ve never used, and schedule a time to explore it. You’ll be surprised how much value is waiting, just beneath the surface of that little plastic card.
Deb Roberts is a freelancer who writes on various subjects, bringing versatility and depth to her work. Alongside her broad writing expertise, she has a special passion for horses.
Related Posts
Value-Based Insurance Design: Turning Coverage into a Strategic Health Asset
Value‑Based Insurance Design aligns cost‑sharing with high‑value care, encouraging preventive ... Read More
Why Small Businesses Should Rethink Health Insurance as a Talent Magnet
Health insurance can be a powerful recruitment tool when positioned as a talent magnet. This post sh... Read More
Navigating Health Insurance: A Holistic Guide to Smart Coverage
A personal, holistic approach to health insurance reveals hidden fees, leverages wellness perks, and... Read More
Top Posts
The Unexpected Power of Financial Planning During Pregnancy
A proactive approach to money management can calm pregnancy stress, improve nutrition choices, support gut health, and strengthen relationships—turning financ...Read More
The Rhythm of Thought: Harnessing Music for Brain Health
Explore practical ways to embed rhythm and melody into daily life, unlocking neuroplastic benefits and emotional balance for lasting brain health....Read More
The Longevity Edge: Harnessing Social Synchrony for a Longer, Healthier Life
Discover how intentional social connection and rhythmic community engagement can act as powerful longevity boosters, improving sleep, immunity, and cellular hea...Read More
Thriving Past 60: A Holistic Roadmap to Healthy Aging
A personal guide to aging gracefully, blending nutrition, exercise, mindset, and community for lasting vitality and resilience....Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!