
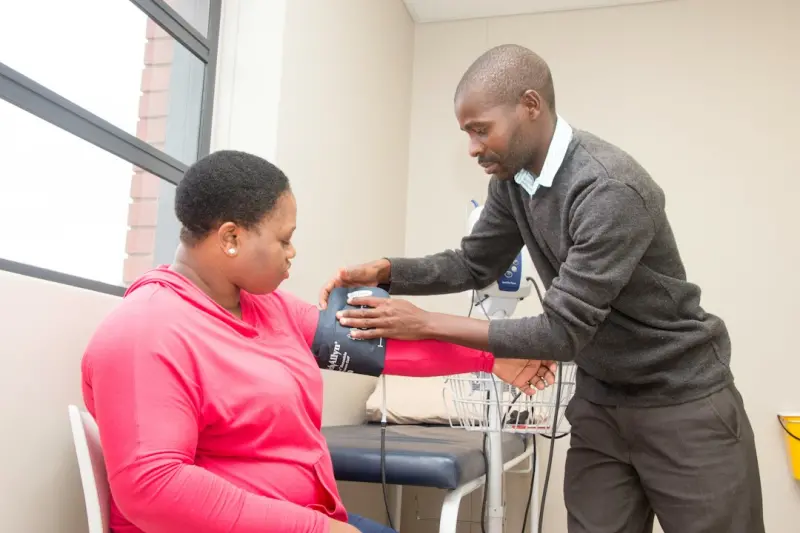
Why Preventive Care Benefits Are the Secret Weapon in Modern Health Insurance
When I first stepped into the labyrinth of employer‑sponsored health plans, I felt like I was trying to decode a foreign language without a dictionary. The fine print was dense, the jargon relentless, and the promises of “comprehensive coverage” often felt more like marketing fluff than real value. Over the past few years, I’ve turned that frustration into a mission: to help professionals like you uncover the hidden gold mines in your health insurance—especially the preventive care benefits that can keep you healthier and keep more money in your pocket.
What Exactly Is Preventive Care?
Preventive care is any health service that aims to stop an illness before it starts or catches it early enough that treatment is simpler, cheaper, and less invasive. Think of annual physicals, vaccinations, cancer screenings, cholesterol checks, and even counseling for mental health or lifestyle changes. While many plans list these services under “covered,” the reality is that you have to know when, how, and why to use them.
The Real Cost Savings: A Numbers‑Driven Perspective
According to the Centers for Disease Control and Prevention, chronic diseases account for 90% of the nation’s $3.8 trillion in annual health care costs. Yet many of those conditions—diabetes, hypertension, certain cancers—are preventable or at least manageable when caught early. A single preventive screening can save thousands in downstream treatment costs. That’s a simple equation: Early Detection = Lower Treatment Expense.
But the savings don’t stop at the macro level. On a personal level, each avoided emergency room visit, each avoided specialty referral, and each reduced prescription cost adds up. If you’re paying a monthly premium of $350, a single avoided $2,000 specialist bill translates to a net gain of over 5% of your annual health‑care spend.
Common Myths That Keep You From Using Preventive Benefits
- “My deductible is too high.” Many people assume that because they haven’t met their deductible, they can’t get anything covered. In reality, the Affordable Care Act mandates that most preventive services are covered without applying to your deductible or co‑pay.
- “I’m healthy; I don’t need a physical.” Even if you feel fine, a routine physical can reveal hidden risk factors—high blood pressure, elevated cholesterol, early signs of metabolic syndrome—that you’d otherwise miss.
- “I’m too busy to schedule a screening.” Telehealth and on‑site employer clinics are making it easier than ever to squeeze a quick check‑up into a lunch break.
How to Audit Your Plan for Preventive Perks
Step 1: Grab the Summary of Benefits and Coverage (SBC). This one‑page PDF is required by law and highlights what’s covered before you meet your deductible. Look for sections titled “Preventive Services” or “Wellness Benefits.”
Step 2: Cross‑reference with the USPSTF Recommendations. The United States Preventive Services Task Force publishes an evidence‑based list of screenings by age and risk. If a service appears there, it’s almost certainly covered without cost‑sharing.
Step 3: Talk to HR or your Benefits Broker. Ask them to confirm any “wellness incentives” like gym membership reimbursements, nutrition counseling, or stress‑management programs. Some plans even offer cash back for meeting step‑count goals.
Step 4: Schedule a “Preventive Care Day.” Block out a half‑day each year to line up all your recommended screenings—blood work, dental check, eye exam, and any age‑specific cancer screenings.
Leveraging Telehealth for Preventive Care
Telemedicine exploded during the pandemic, and the momentum hasn’t slowed. Many insurers now count virtual visits as preventive, especially for routine check‑ins, mental health counseling, and chronic disease monitoring. The convenience factor is huge: no commute, no waiting room, and often lower co‑pays. If your plan includes a telehealth platform, set up an annual virtual wellness check. It’s a quick way to stay on top of your health without sacrificing a day off.
Mind the Gaps: When Coverage Isn’t Enough
Even the most generous plans have blind spots. For example, many insurers cover a basic annual physical but charge extra for a full lipid panel or advanced cardiac risk testing. That’s where real‑time biofeedback can become a game‑changer. By using wearable tech that tracks blood pressure, heart rate variability, and stress markers, you can gather data that supports a deeper conversation with your physician—potentially unlocking coverage for more comprehensive tests.
Another blind spot: mental health. While many plans now list counseling as a covered service, the number of sessions and types of providers can be limited. If you need ongoing therapy, consider supplementing with employer‑run Employee Assistance Programs (EAPs) that often provide a set number of free sessions.
Putting It All Together: A Sample Preventive Care Calendar
| Age Range | Screening / Service | Frequency |
|---|---|---|
| 20‑29 | Blood pressure check, cholesterol (if risk factors), HPV vaccine | Every 2‑3 years |
| 30‑39 | Blood glucose (fasting), skin cancer exam, flu vaccine | Annual |
| 40‑49 | Mammogram (women), colon cancer screening start, diabetes risk assessment | Every 1‑2 years |
| 50‑64 | Colonoscopy, bone density test, cardiovascular risk panel | Every 1‑3 years |
| 65+ | Annual wellness visit, shingles vaccine, vision and hearing test | Annual |
Use this as a baseline and adjust based on personal risk factors—family history, lifestyle, and existing conditions.
Small Lifestyle Tweaks That Amplify Your Benefits
Even the best insurance can’t replace healthy habits. But you can tiny daily moves that reinforce the preventive services you’re already getting. For instance:
- Walk 10 minutes after each meal. This modest post‑prandial stroll helps regulate blood sugar and supports cardiovascular health, making your annual glucose screening more likely to be normal.
- Schedule a “digital detox” hour. Reducing screen time before bed improves sleep quality, which in turn lowers stress hormones that can skew blood pressure readings.
- Take a daily multivitamin with iron and vitamin D. While not a substitute for lab work, consistent supplementation can fill minor nutritional gaps that otherwise might show up in blood tests.
Real‑World Success Stories
Case Study 1 – The Corporate Trainer: Maya works for a tech firm that offers a high‑deductible health plan with a robust wellness stipend. By auditing her SBC, she discovered that annual health coaching was covered 100%. She enrolled in a 12‑week program that focused on diet, exercise, and stress reduction. Six months later, her cholesterol dropped from 220 to 180 mg/dL, and she avoided a $350 co‑pay for a cholesterol‑lowering prescription.
Case Study 2 – The Remote Developer: Alex’s remote‑first company provides telehealth visits for preventive care. He booked a virtual wellness check, during which his doctor recommended a low‑dose aspirin regimen based on a new risk calculator. The doctor also ordered a full cardiac risk panel—covered without a deductible—allowing Alex to catch early signs of arterial plaque. The early intervention saved him from a potential heart attack and the associated high costs.
Future Trends: What to Expect in the Next Wave of Preventive Coverage
1. Value‑Based Insurance Design (VBID) – Plans will increasingly tie coverage levels to the health outcomes of specific preventive services, rewarding members who engage in evidence‑based care.
2. Integrated Wearable Data – Insurers are starting to accept data from FDA‑approved wearables as part of medical records, which could unlock coverage for personalized preventive programs.
3. Expanded Mental Health Benefits – The stigma around mental health is dropping, and many insurers are moving from limited session caps to unlimited counseling, especially via telehealth.
Action Plan: Your 5‑Step Checklist for Maximizing Preventive Care
- Review your SBC today. Highlight every preventive service listed.
- Map the services to your age and risk profile. Use the table above as a guide.
- Schedule at least one in‑person and one telehealth preventive visit this year.
- Leverage wearable data. If you have a device, share the insights with your provider to justify deeper screenings.
- Track your savings. Keep a simple spreadsheet of avoided co‑pays, reduced medication costs, and any employer wellness incentives you earn.
Final Thoughts
Health insurance can feel like a maze, but the preventive care corridor is often the straightest path to both better health and lower costs. By taking a proactive stance—understanding your plan, using telehealth wisely, and integrating small, evidence‑based lifestyle habits—you can transform “coverage” from a safety net into a strategic advantage. Remember, the best defense against disease isn’t a pricey specialty visit; it’s a well‑used preventive benefit that keeps you thriving year after year.
Jessica Hall is a dynamic freelance writer based in the vibrant city of London, Ontario. As a dedicated single mom, she expertly juggles the demands of parenthood with her passion for storytelling, crafting compelling narratives that resonate with readers. With a background in retail, Jessica brings a unique perspective to her writing, infusing her work with insights drawn from her experiences
Related Posts
Health Insurance as Your Hidden Performance Lever
Learn how to treat health insurance as a strategic asset, leveraging preventive care, telehealth, an... Read More
Value-Based Insurance Design: Turning Coverage into a Strategic Health Asset
Value‑Based Insurance Design aligns cost‑sharing with high‑value care, encouraging preventive ... Read More
Health Insurance as a Talent Retention Power Play
A health‑insurance plan isn’t just a cost; it’s a strategic asset. Learn how to design, commun... Read More
Top Posts
Playful Curiosity: A Secret Weapon for Healthy Aging
A deep dive into the science and practical habits of playful curiosity, showing how asking “What if?” daily can sharpen memory, boost social bonds, and keep...Read More
Proprioceptive Mastery: Redefining Physiotherapy for Faster Recovery
Proprioceptive training combined with wearable technology is revolutionizing physiotherapy. Learn why balance, body awareness, and data-driven drills can cut re...Read More
Stepping Into the Future: How Virtual Reality is Transforming Physiotherapy
Virtual reality is turning physiotherapy from routine exercises into engaging, data‑rich experiences. Discover the science, real‑world success stories, and ...Read More
Muscle Gain From My Lens: A Holistic Blueprint for Sustainable Strength
Kelly Reynolds shares a holistic, sustainable muscle‑gain strategy that blends smart nutrition, progressive training, recovery, and mental resilience for last...Read More
0 Comments
Post Comment
You will need to Login or Register to comment on this post!